


Nest Notes
Should You Give Up Your Low Mortgage Rate to Buy a New Home?

October 2, 2026
Should You Give Up Your Low Mortgage Rate to Buy a New Home?
Sometimes yes and sometimes no. Your low rate has real value, and so does the space, layout, or lifestyle your current home isn't giving you. If you're asking whether you should give up your low mortgage rate to buy a new home, the honest answer is that it depends on what the math actually shows you, not on what the rate alone seems to say. Here's how we'd walk a friend through weighing it.
This is general education, not financial advice. Every example below uses round, hypothetical numbers so you can see how the comparison works. Your actual numbers will come from your lender and your own budget.
Key Takeaways
- Your mortgage rate does not transfer to a new home. A new loan starts at today's rate, which is why the payment on a similar home is often higher than what you pay now.
- The gap between your current payment and a new one is the real price of moving. That number, not the rate itself, is what deserves your attention.
- A low rate comparison leaves out what your home may no longer give you: enough space, the right layout, or a location that fits your life now.
- Equity, selling costs, taxes, insurance, and lower maintenance in a newer home all belong in the math, not just the interest rate.
- Builder rate incentives, a larger down payment from equity, right-sizing instead of upsizing, and Quick Move-In pricing can all soften a higher payment.
- Staying and renovating is a legitimate option, not a consolation prize, for households whose home still has good bones.
- The simplest test is this: what would you pay each month for the life you actually want to be living?
- Use a Buying Power Calculator before you decide anything. See the real number first, then weigh it against your current one.
Why So Many Owners Feel Stuck to Their Rate
A mortgage rate lock in effect means your current rate is tied to your current loan on your current home. It doesn't move with you. When you sell and buy again, you're financing the new home at whatever rate is available at that time, which is often higher than the one you have now, even for a home similar in size and price.
This is the core of what's often called being stuck in a low rate mortgage. You're not stuck because your house is wrong for you. You're stuck because the next loan resets the clock, and that reset is what makes so many owners pause before listing their home.
It's a real constraint. It's not a reason to assume moving is off the table, and it's not a reason to assume it's fine either. It's the thing to measure.
What Your Low Rate Is Actually Worth
Here's where the math starts, using illustrative numbers only.
Say your current loan is $300,000 at 3%. Principal and interest come to roughly $1,265 a month. Now say you'd finance a similar-priced home at 6%. The payment on that same loan amount jumps to around $1,800 a month. That's a difference of about $535 a month, or roughly $6,400 a year, just from the rate.
That gap, whatever it turns out to be for your numbers, is the price of giving up your rate. It's not hidden and it's not complicated. It's the first number to calculate, and it's the one most owners stop at.
But it's not the only number that matters.
What the Payment Comparison Leaves Out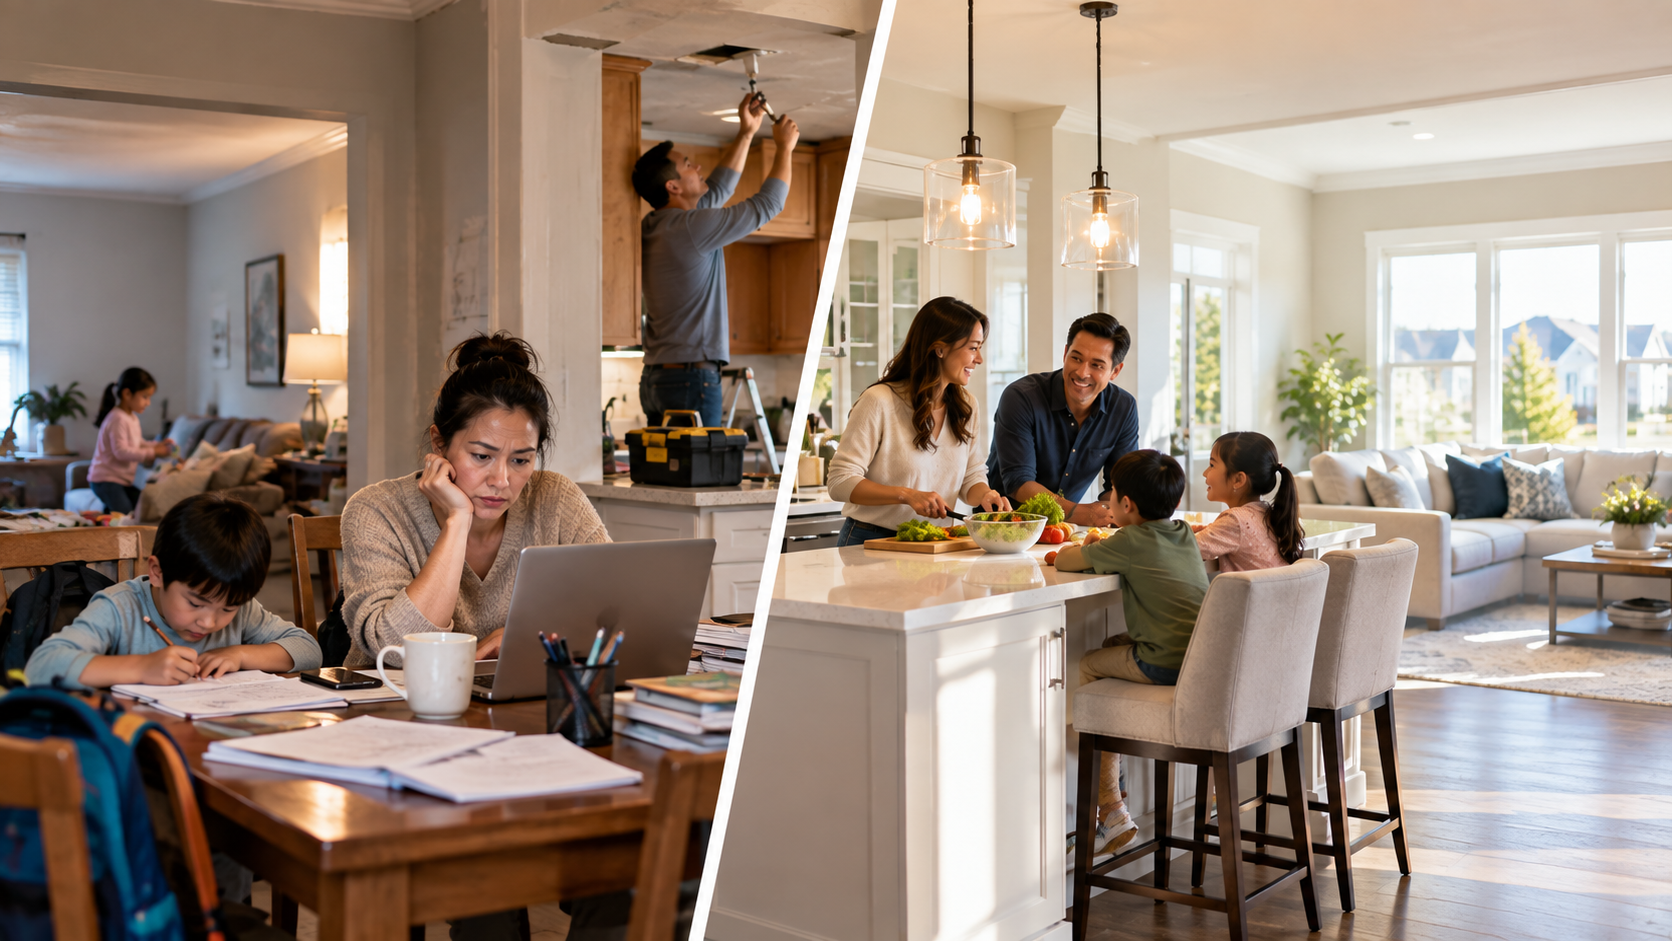
A rate comparison tells you what a loan costs. It doesn't tell you what staying put costs.
If your current home no longer has enough bedrooms, a workable layout for how your family actually spends its day, or a yard, office, or storage space you need, that's a cost too. It shows up as frustration, as a cramped routine, as a home office carved out of a dining room nobody uses anymore. It's real, even though it doesn't have a line item.
Repairs and updates matter here as well. A roof at year eighteen, a furnace on its last few winters, kitchen cabinets that were dated when you bought the place: these costs are coming whether you move or not. If you stay, they're yours regardless of your rate.
And there's a cost to time itself. Another year or two in a home that doesn't fit isn't free. It's a year or two of living around a problem instead of solving it, at a stage of life you don't get back.
The Rest of the Math: Equity, Costs, and Savings
The full comparison includes more than the monthly payment difference. It includes:
- Equity. If you've owned your home for several years, you likely have built-up equity you can put toward the new home, which lowers the amount you finance and softens the new payment.
- Selling costs. Agent commissions, closing costs, and any repairs needed to sell come out of your proceeds before that equity reaches your next down payment.
- Property tax and insurance. These vary by home and location and can shift the monthly comparison in either direction. A newer home in a different township or school district may carry a different tax bill than you expect.
- Maintenance. A newer home typically needs less in the first several years. New systems, new roof, new windows, and a warranty behind the work mean fewer surprise repair bills stacked on top of the new payment.
Run all of it together, not just the rate difference, and the real gap is often smaller than it looks at first glance.
Ways Buyers Soften the Jump
Move up buyers dealing with a low rate on their current home have more options than simply absorbing the higher payment.
Builder rate incentives can reduce the rate on the new loan for a period or for its full term, closing part of the gap directly. A larger down payment, funded by the equity in your current home, lowers the amount you finance and the payment that comes with it. Choosing a similar-size home instead of a bigger one keeps the loan amount closer to what you have now rather than stretching it further. And a Quick Move-In home, already built or nearly finished, is often priced to move and can come with its own incentives that a to-be-built home does not.
We offer programs like Garman Pathways™ that are built around exactly this kind of flexibility, including rate support and a lower upfront cash requirement, so the jump from one payment to the next is something you can actually plan around rather than guess at.
When Staying and Renovating Makes More Sense
For some households, the better move is no move at all. If your home's layout, size, and location still work, and what's missing is really a kitchen, a primary suite, or an addition, renovating can solve the real problem without touching your rate or your loan at all.
This isn't the fallback option. It's the right answer for a household whose home fits but needs updating. The test is the same either way: does the home work for how you live, or does it not?
When Moving Makes Sense
Moving makes sense when your current home no longer works for how you live and the new payment fits comfortably into your budget. It also makes sense when timing matters more than the rate: a growing family, a job change, aging parents, or a stage of life that your current home simply can't support, regardless of what the mortgage math shows.
When Staying Makes Sense
Staying makes sense when your home still works for your life and the new payment would strain your budget. If the rate gap, once you've accounted for equity, incentives, and lower maintenance, still leaves you tight every month, that's real information. A home that fits your life but not your budget isn't a win, even if the layout is perfect.
The Simple Test: What Would You Pay for the Life You Actually Want?
Set the rate aside for a moment and ask one question: what would you pay each month for the home and life you actually want, if the rate weren't part of the decision at all? Compare that number to what the new loan would actually cost you. If they're close, the rate is the only thing standing between you and a decision you'd otherwise make easily.
See Your Real Number Before You Decide
The only way to know where you stand is to run your own numbers, not someone else's example. Our Buying Power Calculator shows you what a new payment would look like based on your situation, your equity, and current rate options, so you can compare it honestly to what you're paying now.
Use the Buying Power Calculator
From there, our team can walk you through Quick Move-In pricing, Garman Pathways™, and the communities across Lancaster, Lebanon, Cumberland, York, and Perry counties that might fit both your life and your budget. There's no pressure in that conversation. The right answer is the one that fits your life and your budget, and it's fine if that answer is staying put.
Frequently Asked Questions
Does my current mortgage rate transfer to a new home?
No. Your rate is attached to your current loan. A new mortgage on a new home is financed at whatever rate is available at the time of your new loan, which is often different from your current rate.
How much more could my monthly payment be on a new home?
It depends on your loan amount and the rate you qualify for, but the gap is calculable before you commit to anything. A Buying Power Calculator or a conversation with a lender can show you the real number for your situation.
Is it ever smart to give up a low mortgage rate?
Yes, when your current home no longer fits how you live and the new payment fits comfortably in your budget once equity, incentives, and lower maintenance costs are factored in.
What does mortgage rate lock in effect mean?
It describes how homeowners with low rates hesitate to sell because their next loan will reset at a different, often higher, rate. It's a documented pattern across the housing market, not a reflection of any one home or buyer.
Can builder incentives offset a higher rate?
Often, yes. Rate buydowns, down payment support from your home's equity, and Quick Move-In pricing can all reduce the gap between your current payment and a new one.
Is renovating a better option than moving?
For households whose home's size, layout, and location still work, renovating can solve the real problem without changing your loan or your rate at all. It's a legitimate choice, not a fallback.

 0